
For the past 2-3 years, I have been meeting parents who want to plan for the safety and financial support of their child and I often hear the question: “Where is the best place to invest my child’s allowance?”
Parents are starting to adopt the model from abroad where higher education planning is done in the first years of the child’s life or even before he or she is born. Supporting the child most often involves paying tuition at a university abroad and living there. In addition to this purpose, parents also plan to financially support a business if their child, who has reached the age of majority, wishes to do so or for the purchase of their home (full payment or down payment and furniture).
Well, I have already written an article about solutions for financial support for a child https://www.e-learning.psihologiabanilor.ro/conturi-de-economii-pentru-copii/, but this time I come with concrete calculations; however, I will not give names of companies and products specifically, but only the names of the categories of financial products; a preamble to what you can find in the book: “Investment Methods” which is currently in pre-launch.https://www.e-learning.psihologiabanilor.ro/product/e-book-cum-sa-iti-gestionezi-banii-metode-de-investitii/
If you have suggestions for product categories that I should analyze, if you have questions that you want to find the answer to in such a book, I invite you to write to me in the comments because I still have 10% to write on it and I can add information in case I omitted the information you want.
Come on let’s see what you can invest your child’s allowance in!
However, because, again, I often hear parents who want to invest in the “safest investment”: rental property, I start with this investment, although to buy a property you don’t have all the money from your 18-year-old child’s allowance.
I invest in a property in:
-
hotel regime
- at the seaside
- 2 ca 135000 euros
- Furniture: 2500 x 4 = 10,000 euros
- Rent: 350 lei/night x 22 days (75% occupancy) = 7,700 lei/month
- Costs: cleaning, insurance, rental agency commission, tax
- Earnings 4 months/year = 7700 x 4 = 30,800 lei /year
- 145,000 euros = 725,000 lei : 30,800 = 23.53 years
Yield: 4.24% gross
! In real estate investment, to be profitable, it is recommended to have a yield of at least 6%/year
- With credit:
- 15% down payment = 20,250 euros + furniture: 10,000 + documents: 2,000 euros = 32,250 euros
- Instalment: 3,000 lei
- Monthly income: 30,800: 12 = 2,566 lei
-
in the mountains
- Ap 2 ca 135000 euros
- Furniture: 2500 x 4 = 10,000 euros
- Rent: 350 lei/night x 22 days (75% occupancy) = 7,700 lei/month
- Costs: cleaning, insurance, rental agency commission, tax
- Earn 12 months/year = 7700 x 12 = 92,400 lei /year
- 145,000 euros = 725,000 lei : 92,400 = 8 years
Yield: 12.74% gross
Costs: tax, insurance, cleaning, photos (for the apartment), listing on promotion platforms and promotion costs, repairs.
We can say that it can even reach 5-6%/year yield
-
Credit:
- 15% down payment = 20,250 euros + furniture: 10,000 + documents: 2,000 euros = 32,250 euros
- Instalment: 3,000 lei
Monthly income: 7,700 lei – 3,000 lei = 4,700 lei
Yield: 34%/year gross
-
in an urban area that is not touristic
- If the property is purchased in cash, then the profit would look like this:
- 000 euro apartment price + 10,000 euro furniture + 10,000 euro renovation (over time – over 30 years) = 90,000 euro = 450,000 lei
- 200 lei/night x 22 days (75% occupancy) = 4400 lei /month
- Amortization: 102 months = approx. 9 years
- ROI: (4400×12) / 450,000 x 100 = 11.73%/year GROSS
- If the property is purchased on credit, then the profit would look like this:
- 7000 euros apartment price
- minimum 15% down payment = 10,500 euros – 1,500 euros documents – 10,000 euros furniture (and/or renovation) = 22,000 euros own money
- loan for 70,000 – 10,500 = 500 euros
- rate: 1455 lei
- 200 lei/night x 22 days (75% occupancy) = 4400 lei /month
- Difference: 2945 lei
- ROI: (2945 x 12) / 110,000 lei x 100 = 32% GROSS
-
traditional regime
-
If the property is purchased in cash
Ex. 70,000 + 10,000 + 10,000 = 90,000 E
90,000: 350=257 months = 21 years
Amortization
ROI: 350 x 12/90,000 x 100= 4.6%
- Costs: tax (6%+10%), property insurance (PAD+fac= 300 lei/year)
-
If the property is purchased with credit
Ex. 70,000
- 10500 + 1500 + 10000 + 10000 = 32,000 euros = 160,000 lei
- Instalment: 1458 lei
- Rent: 1750 lei
- Difference: 292
- ROI: (292×12): 160,000 lei x 100 = 2.19%/year GROSS
- Costs: tax (6%+10%), property insurance (PAD+fac= 300 lei/year)
- And the 75% occupancy requirement.
Invest in a special bank account for children
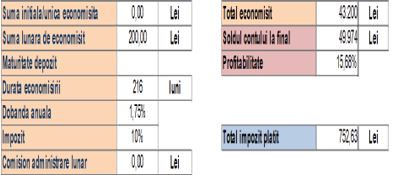
These “special bank accounts for children” actually have the word: “child” in their name because they are part of the category of either savings accounts or bank deposits. Their conditions are the same, only the name differs.
I invest in a mutual fund

The mutual fund is accessible to the general public, but it is an unguaranteed product, which allows access to money, which can disadvantage the child, since the parent may choose to change their curtains in the event of a renovation or change their car or use this money for various other expenses for the child instead of saving them for his/her studies or for a business or for a down payment on the child’s house
– objectives that are distant but which are more expensive exceeding the monthly income budget at that moment: the child’s age of 18 or 20/25 years.
I invest in a capitalization life insurance

Capitalized insurance allows for the generation of a larger amount because the capitalized interest takes effect. The longer the period, the greater the amount obtained.
The disadvantage of not “getting into money” can be an advantage: that of accumulating a larger amount. For unforeseen situations, there are emergency savings and financial security funds.
This product category is guaranteed and if the parent dies, the child will have the guaranteed amount: the amount that the parent “committed” to saving for his or her child.
I invest in annuity insurance for studies
Amount deposited: 200 lei per month
Duration: 18 years
Amount deposited: 43,200 lei
Amount insured: 46,200
Profit = amount insured – amount deposited = 3,000 lei = 13.88 lei/month
It is also a guaranteed product, a product that can be used at the end in the form of an annuity – that is, part of the amount at the end is divided into 3 or 5 years to use for tuition fees, but it does not have to be proven that a level of education is being followed, simply, the money is taken in installments as initially established; if you want to give up the idea of tranche, it is considered a contract termination and the amounts received are 5 to 10% lower.
I invest in investment insurance (unit-linked)
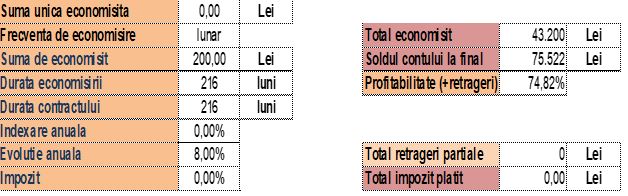
It is an investment fund wrapped in insurance to avoid paying income tax. It is a flexible product (depending on the company) where you can access the money or stop deposits and the money remains to be invested further, to receive capitalized interest. There is a team of brokers who invest the money according to the market on different classes of financial instruments and in different weights, which allows for a good return.
It is a guaranteed product in that it falls into the insurance category with a guarantee fund of 90,000 euros according to the law.
I invest in an ETF

The ETF is a basket of shares. You choose to invest in a certain basket – the one you like – depending on the areas in which it is invested. The disadvantage of such a basket is that there is no dynamism to change the proportion in which it is invested because for a period of time a field or a company works better. It is a passive investment that will generate a higher or lower profit depending on the sector in which you have invested.
Being a basket of shares there is diversification, however there is no guarantee of this type of investment, and flexibility may or may not be an advantage.
The fact that you do not invest in individual shares offers you greater security, a low energy consumption allocated to analyzing companies.
Investing on the Stock Exchange
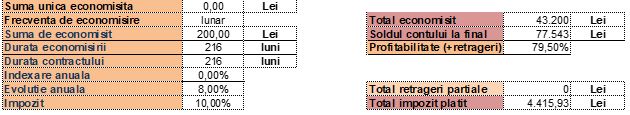
Investing in the Stock Market requires time and involvement in analyzing the companies from which you want to buy shares/bonds. There are two types of analysis that you need to do in order to make the best decisions: technical and fundamental analysis, and I recommend both, in parallel.
The disadvantage of this option is the involvement of time, energy and knowledge as well as the risk of losing money by choosing a company/companies that may go bankrupt.
The stock market is a marketplace that allows you to invest on your own and have the freedom to choose what to do with your money, and with the pandemic, many people have opened trading accounts on the Stock Market, which has led to a decrease in the amounts to be invested. A broker in our country has reduced the minimum initial amount from 10,000 lei to 3,000 lei.
Invest in crypto

Virtual currencies are a form of investment that has created a wave of investors, especially among young people or / and programmers: a new, revolutionary field. It is an unregulated field, a speculative and risky field (the risk itself being that of losing money). The human psychological desire to earn quickly and easily has determined this wave of investors in the crypto area, which has allowed the explosion of virtual currencies created.
Virtual currencies have a project behind them, a project that supports a technological industry, the IT infrastructure, and the greater, more important, wider the support, the more that currency appreciates and is more durable.
I recommend this investment only as a third investment, having several safe investments behind it (at least two). And I do not recommend investing children’s money in this investment because there is a risk that we will not be able to support our child when they reach adulthood with the proposed objectives.
And I end with a state program, often mentioned by parents.
I invest in the state program (Junior Centenar)

- 600 lei/year for 18 years = 10,800 lei
+ = 68,130 lei
The investment through the state program that offers a bonus to support parents’ objectives targets a considerable amount, but which is not capitalizes, which makes it a very good product in the short term when the capitalized interest does not have time to take effect. You can find more about capitalization here:
https://laurentiumihai.ro/puterea-dobanzii-compuse/
The money is guaranteed, and the lack of tax represents two features – real benefits for parents.
 The psychological context of planning child support and investments for him
Not all parents want to support their children. There are three categories of parents: those who do not want to support their children financially when they come of age, because they think: “I was not supported either and I managed, so let him manage too!”, those who want to support their children within a certain limit: “just with their studies, with college, let him manage the rest!
If he wants to start a business with his own money, with his work and if he wants a house to make the necessary money and the necessary actions, only then will he become a responsible adult! I will offer him moral support and I will give him financial education in childhood so that he knows what to do in his financial life”. And there are also those parents who want to support him with all the objectives discussed at the beginning of the article: with a house, studies and a business: “we also supported him (and maybe we still are supported) and we want to support him” or “we were not supported so we will support our children as long as it takes, including the grandchildren”.
None of the categories are not, none of them are wrong ways of thinking, but it is necessary to be aware of how we want it to be in our case and to act accordingly. And as such, let’s go for the solution that suits us, that fulfills our child’s support needs.
Which one suits you? What do you see as more profitable for the investment of your child’s allowance?
Write to me if you want to discuss a personalized choice. I offer personalized advice as an independent, authorized financial consultant.https://www.e-learning.psihologiabanilor.ro/consultanta-financiara/
For more general information about the products on the market, you will find it in the book that will be released this year: ”Investment Methods” which you can pre-order here:
And to interact with me and financially educated people, I invite you to the Facebook group: “Psychology of Money”.https://www.facebook.com/groups/psihologiabanilor
This article is not a material in which an investment decision can be made!
A thorough financial analysis and consultation with a specialized and authorized consultant can provide all the information necessary to make a decision.
In general, I recommend that you do not make financial decisions based on an article or a book you read about your finances and that you contact a specialist asking them to tell you what their competence is and their authorization by a state-recognized professionalization institution (there are 6 on the market).
Calculations may vary from company to company, from one period to another, therefore an informed and responsible decision based on an up-to-date analysis is necessary.
Comparisons are made based on the costs of each type of product and the performances they record on average.



 ©2025 PSIHOLOGIA BANILOR - All Rights Reserved - Powered by


